Single-Family Home vs. Condo: Chicago Investment Guide
Chicago Real Estate, Home Buying Guide, Property Comparison
Single-Family Home vs. Condo in Chicago: Which Is a Better Investment?
Choosing between single-family homes and condos in Chicago is one of the most important decisions you will make as a buyer or investor. Both options can perform well in today’s market, but the “better” investment depends on your budget, lifestyle, and long-term goals.
Snapshot of the Chicago Real Estate Market in 2026
Chicago real estate in 2026 is defined by steady price growth and still-tight inventory. Citywide, median sale prices for all home types hover around $395,000–$420,000, with year-over-year appreciation in the 5–6% range (based on recent reports from Redfin and Here & Now Chicago). Homes are selling in roughly 47 days on average and typically receive about three offers, signaling a market that still favors sellers but is more balanced than the frenzied pandemic years (Redfin).
For investors, rising rents add another layer of opportunity. Metro-area median rent has climbed around 4% year-over-year to roughly $1,670 per month, with some downtown and lakefront neighborhoods commanding substantially higher rents. At the same time, new construction has not fully kept pace with population gains, which helps support both rental demand and long-term price growth.
Single-Family Homes in Chicago: Space, Stability, and Strong Appreciation
Single-family homes have been standout performers in Chicago. As of mid-2026, city single-family median prices generally range from about $420,000 to $510,000, with year-over-year gains of 5–9%, and even higher in some years (Homes.com, iBuyer.com). A Harvard Joint Center for Housing Studies report also notes a 5.6% annual increase for existing single-family homes in the early part of 2026.
For many buyers, single-family homes are the classic Chicago investment: think brick bungalows on the Northwest Side, historic greystones in Logan Square, or updated cottages in Bridgeport and Pilsen. These properties typically offer:
More space and privacy — yards, basements, and no shared walls, ideal for long-term residents and families.
Greater control over the property — you make the decisions on upgrades, landscaping, and maintenance timelines without a condo board’s approval.
Potential for higher appreciation in land-constrained or gentrifying neighborhoods, especially where new single-family supply is limited.
From an investment perspective, single-family homes can be powerful wealth builders. They often attract long-term renters willing to pay a premium for space, garages, and outdoor areas, particularly in school-strong areas like Lincoln Park, Lake View, or portions of the Northwest Side. However, they also come with higher upfront costs, potentially larger down payments, and full responsibility for maintenance and repairs.
💡 Home Buying Guide Tip: When evaluating a single-family home, budget 1–2% of the property value per year for ongoing maintenance, especially for older Chicago housing stock.
Condo Investment in Chicago: Lower Entry Cost and Turnkey Convenience
Condominiums play a major role in Chicago real estate, particularly in downtown, Near North Side, South Loop, West Loop, and along the lakefront. For many buyers, a condo investment offers a more affordable entry point compared to single-family homes in the same neighborhood, plus access to amenities like gyms, doormen, and shared outdoor spaces.
If your strategy is to rent the unit out, condos can be especially appealing in high-demand rental corridors where young professionals prioritize walkability and transit access. Strong rent growth in the broader multifamily sector — with metro occupancy above 95% and effective rents around $1,900 per month in late 2026 (MMG Real Estate Advisors) — suggests that well-located condos can enjoy steady demand and low vacancy.
Pros: Lower purchase price than comparable single-family homes, shared maintenance, attractive amenities, strong appeal to renters who value location and lifestyle.
Cons: Monthly HOA fees, special assessments, and potential rental restrictions can impact cash flow and flexibility.
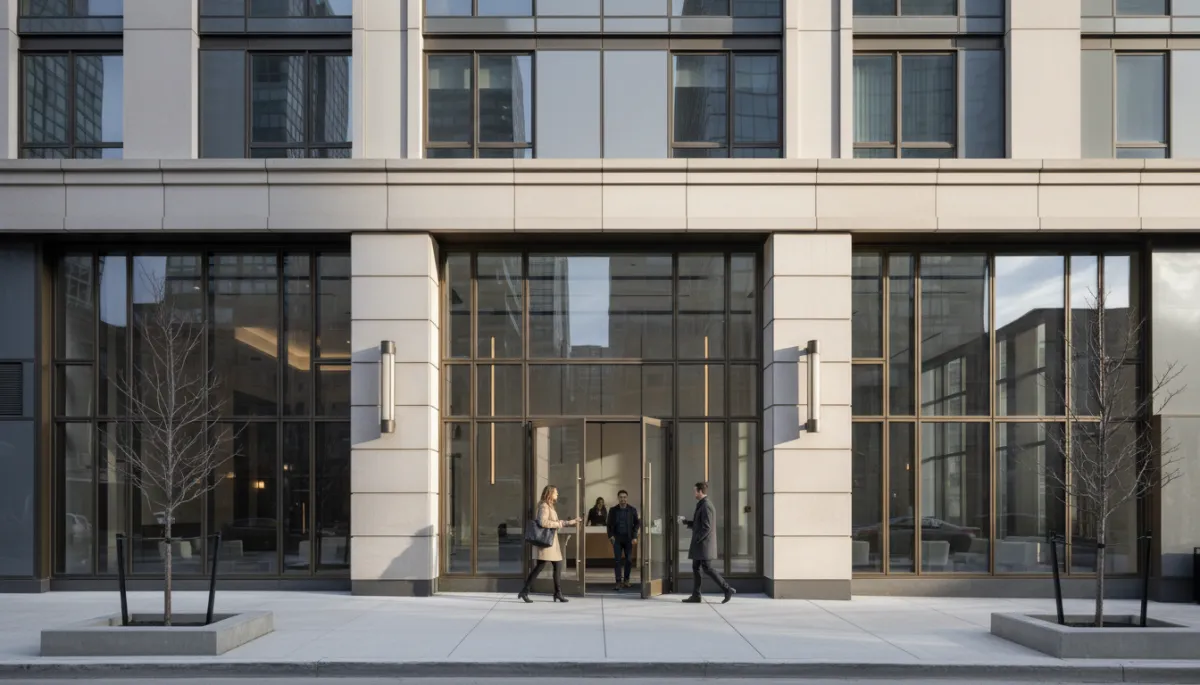
Well-managed condo buildings can offer stable rents and lower hands-on maintenance for investors.
💡 Condo Investment Tip: Always review the building’s financials, reserve fund, and rental policies. A strong association and healthy reserves can protect you from surprise assessments.
Property Comparison: Single-Family Home vs. Condo in Chicago
Factor Single-Family Homes Condos Typical Price (City) ~$420K–$510K, higher in top neighborhoods Often lower than nearby single-family homes Appreciation Potential Strong, especially where land is scarce Moderate to strong in prime buildings and locations Maintenance Owner handles all upkeep and repairs Shared via HOA; fewer day-to-day tasks Monthly Costs Mortgage, taxes, insurance, utilities, upkeep Mortgage, taxes, insurance, plus HOA dues and assessments Rental Demand Strong with families, long-term renters, and pet owners Strong with young professionals and urban lifestyle seekers
A Practical Home Buying Guide for Chicago Investors
Whether you lean toward a single-family home or a condo investment, a clear framework will help you compare properties and avoid surprises. Use the following steps as a concise Chicago-focused home buying guide:
Clarify your primary goal. Are you buying a home to live in for at least five years, or are you prioritizing rental income and long-term appreciation? End users may value space and schools; investors may favor neighborhoods with strong rent growth and low vacancy.
Set a realistic budget. Factor in not only purchase price but also closing costs, inspection fees, reserves for repairs, and for condos, HOA dues and potential assessments. In a market where prices are still climbing 4–6% annually, build in a cushion for bidding above list price on competitive listings.
Choose the right neighborhood. Chicago is a city of micro-markets. High-demand areas like Lincoln Park, Lake View, Logan Square, and the Near North Side have seen price increases of nearly 7–12% in recent data (Kernahan Group). Up-and-coming neighborhoods may offer better cash flow and future upside.
Run the numbers. For each property, estimate your total monthly costs and compare them with realistic rent projections or your own affordability. Include taxes (which vary significantly by ward), insurance, HOA dues, and maintenance. Aim for a cushion so you are not cash-flow negative if rents soften or expenses rise.
Understand policy and assistance programs. Chicago’s HomeGrown Purchase Assistance Program, for example, is injecting millions into down payment and closing cost support, which may improve affordability for qualifying buyers (Axios). For investors, stay informed about local regulations around short-term rentals and landlord-tenant law.
📌 Key Takeaway: The best property comparison is not just condo versus single-family; it is specific address versus specific address, with numbers and neighborhood trends laid side by side.
So, Which Is the Better Investment in Chicago — Single-Family or Condo?
In today’s Chicago real estate market, both single-family homes and condos can be smart investments, but they shine in different scenarios:
Choose single-family homes if you want maximum control, strong long-term appreciation, and the ability to attract stable, long-term tenants or to grow into the home yourself. This path suits buyers with higher budgets and a willingness to manage maintenance or hire it out.
Choose a condo investment if you prefer a lower entry price, shared maintenance, and a lock-and-leave lifestyle in highly walkable, transit-rich neighborhoods. This can be ideal for first-time buyers, out-of-town investors, and those focused on rental income rather than yard work.
Ultimately, the “better” investment is the one that aligns with your finances, risk tolerance, and lifestyle. In a city where single-family prices are climbing and rental demand remains strong, a carefully chosen property — whether a classic Chicago bungalow or a sleek downtown condo — can become a powerful building block in your long-term wealth strategy.
If you are on the fence, start by touring both property types in two or three target neighborhoods. Compare real numbers, not just listing photos. With a clear home buying guide, a grounded property comparison, and an understanding of current Chicago real estate trends, you will be well positioned to choose the investment that works best for you in 2026 and beyond.